


Edition 23 - The Financial Services and Markets Bill 2026
Posted on: 23/09/2026
A Payment Choice Alliance Newsletter
The Financial Services and Markets Bill 2026 - A Genuine Opportunity to Start Restoring In-Person Banking Services to Communities Around the UK!
The 2026 Financial Services and Markets Bill will reach the House of Commons in October 2026.
Paragraph 3 of the Bill is of particular interest to those concerned about the diminution of access to in-person Community Bank Services created by the closure of, on average, around a dozen bank branches every week since January 2015. That’s well over 7000 branches lost, along with the 24/7 ATMs located in their walls.
Here is the relevant paragraph, in Part 1 of the Bill:-
3: Access to Banking Services
- The Treasury may by regulations make such provision as they consider appropriate in connection with providing access to banking services.
- In making regulations, the Treasury must have regard to any recommendations of the independent review into in-person banking access, announced by the Economic Secretary to the Treasury in a statement to the House of Commons on 14 May 2026.
Not very much space in the Bill for such an issue, considering that it is vitally important to millions of members of the British public, living in thousands of communities left without bank branches and 24/7 ATMs.
Richard Lloyd OBE is the person selected by HM Treasury to conduct the Access to Banking Services Review. However, HM Treasury seems to have limited the scope of the Review to identifying only those groups of UK residents for whom access to in-person banking services is a ‘requirement’ - or put another way, absolutely essential.
Richard Lloyd issued the following explanation of the scope of his work.
“There may be several different types of groups, including those who are vulnerable or have specific needs, that rely on access to in-person banking services. There are also those who desire or prefer to have access to in-person banking; however, this Reveiw is focused on those who require access.”
It is quite wrong that HM Treasury is seeking to ignore those who ‘desire or prefer’ to have access to in-person banking.
In May 2026, YouGov carried out research for the Payment Choice Alliance.
To the question:
“How important, if at all, do you think it is to have access to a physical bank branch in your local area?”
76% of the adults responding confirmed that it was either very or fairly important to them to have local access to a physical bank branch.
76% of UK adults equates to around 44 million people, spread around every constituency in the UK.
To the question:
“Thinking of the future of banking and the ways to bank, which of the following best reflects your view?”
53% of adults responded that it should be equally possible to use a physical bank branch and online banking for everything, with a further 36% making clear that they believe that there are at least some situations in which use of a physical bank branch should be possible.
The YouGov research findings are broadly in line with research carried out in 2026 on behalf of the UK Post Office. That research found that 68% of the public want face-to-face banking services close to home and 48% use in-person banking services at least once a month.
In short, access to Community Banking Services, including 24/7 cash access, is NOT a minority interest.
44 million UK adults “desire and prefer” to have in-person Banking Services in their communities.
The Payment Choice Alliance has submitted detailed proposals to Richard Lloyd covering how the desires and preferences of the UK public can be met. However, there is a danger they will be ignored given the limited intended scope of his work.
The first key recommendation of the Payment Choice Alliance is:
- A minimum of 1200 Full-Service Banking Hubs are required, so that every UK community with 5000 or more residents that has previously enjoyed access to in-person bank branch services can automatically have such a Hub. All Hubs should operate six days per week and provide a full range of advice services, along with 24/7 cash access. Other communities should be able to apply to an independent Regulator - the Financial Conduct Authority or similar - to be considered for a Banking Hub.
This recommendation, if implemented, will end the current process, which often involves MPs having to “beg” LINK ATM Scheme to be granted Banking Hubs for communities in their constituencies. Such pleading is often not successful, which is hardly surprising, given that the bank-owned Cash Access UK - which opens Banking Hubs after requests from LINK - has committed to opening only 350 Banking Hubs in total by 2029.
350 Banking Hubs CANNOT replace the 7,000 plus bank branches lost by communities around the UK. Nor, therefore, can such a low number satisfy the clearly stated desires and preferences of 44 million UK adults.
The second key recommendation of the Payment Choice Alliance is:
- Changes to UK banking services have for many years been made to suit UK banks, with insufficient regard for the public interest. To rebalance this, funding for community banking services, including ATMs and other cash access services, should be provided via a levy on bank profits, with an appropriate Regulator responsible for setting the level of the levy annually.
The Big Five UK Commercial Banks; (Barclays, HSBC, Lloyds, NatWest and Santander UK), each of which had to be rescued in one way or another during the banking crisis of 2008/09, have been given far too much latitude to reduce in-person Community Banking Services, including 24/7 cash access.
Time to redress the balance, in the public interest.
44 million UK residents deserve to have their desires and preferences given a very high priority.
MPs can start to ensure this happens via the Financial Services and Markets Bill 2026.
An Excellent Article, by Award Winning Journalist Martin Williams, which Appeared in the Herald Newspaper on 8 September 2026
Click here to read the article in full.
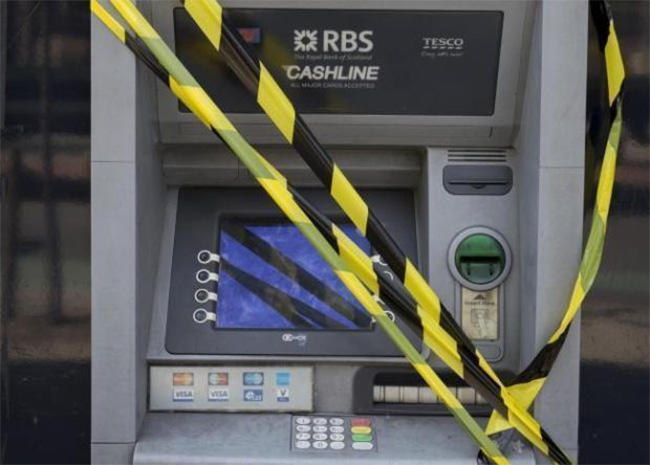
Scots - and many other members of the public in the UK - are finding it increasingly inconvenient to access the cash they continue to want to use.
Time for action, including the restoration of 24/7 ATM services in communities in Scotland - and indeed, everywhere else in the UK.

Please Tell Your Friends About The Payment Choice Alliance
The PCA needs all the active supporters we can get! So please tell your friends about YOUR support for the Payment Choice Alliance - and urge them to visit our website to register THEIR support!
THANK YOU.
About Us
The Payment Choice Alliance, founded in 2014 and relaunched in 2023, is a campaigning organisation committed to ensuring the right of the British public to use cash is safeguarded by the passing of a Payment Choice Act.
The Act would give everyone in the UK the right to use their cash, when and where they choose.
The Payment Choice Alliance, which is run by committed volunteers, is also focused on ensuring every community in the UK has convenient cash withdrawal and deposit facilities. The provision of such facilities, along with the legal obligation of businesses to accept cash, will ensure cash remains a viable Payment Choice for the British public for as long as they want to use it.


All rights reserved. No part of this website can be reproduced, shared or transmitted in any form or by any means without the prior permission of the copyright owner.